
The claim in this panel worth arguing about is that the native currency for AI agents will be crypto — because agents will not carry bank cards or swipe credit cards, and blockchain is the interface most native to them (15:03).
It comes from someone with an obvious interest in it being true, which is a reason to examine it rather than dismiss it. The argument is not about consumer preference or ideology. It is about which rails a machine can use without a human present.
The part of the argument that holds
Existing card networks assume a cardholder. The infrastructure around them — dispute resolution, chargebacks, identity verification, fraud scoring based on behavioural patterns — was designed around a person who can be contacted, who can attest that a transaction was or was not theirs, and whose behaviour forms a baseline.
An autonomous process transacting on its own behalf breaks each of those assumptions. Not because the technology cannot handle it, but because the recourse mechanisms have no one to appeal to.
That is a genuine structural gap, and it is the strongest version of the argument. A payment system where settlement is final and identity is a key rather than a person fits an automated counterparty more naturally than one built on reversibility.
The part that does not follow
What does not follow is the conclusion. The absence of a person is a problem for the current rails, not evidence that the replacement must be the one being proposed.
Banks have built machine-to-machine payment systems for decades. Nothing prevents a card network from issuing credentials to a delegated agent with spending limits and revocation, and several are visibly attempting it. The question is which arrives first and which regulators will accept — a competitive question, not a technical one.
The panel's most direct voice makes the counter-case bluntly: these are high-risk areas where value is highly speculative and building use cases is genuinely hard (24:04), delivered with an acknowledgement that it will annoy people, including in his own industry (23:12).
Both positions can be right. Exchanges and stablecoins are described as the two proven businesses (14:08), and stablecoins are precisely the instrument an agent-payment argument needs — settlement-final, programmable, and not dependent on price speculation. The speculative assets and the payment rail argument are separable, and the panel treats them as one thing.
Tokenisation as the quieter claim
The more consequential item passes with less attention: conversations with roughly a dozen governments about tokenising instruments (14:08).
Government issuance changes the character of the discussion. A tokenised sovereign instrument is not a speculative asset; it is existing debt with different settlement properties, and it arrives with the credit standing of the issuer rather than of a protocol.
If that happens at scale, the infrastructure argument stops depending on whether crypto assets hold value, because the thing moving across the rails is a government obligation. That is a far stronger foundation for the agent-payments claim than any of the assets discussed, and it gets one sentence.
What the incumbents say instead
The traditional-finance response converges on a single word. Everything comes back to trust, and the innovations that thrive will be those that hold customer trust while meeting a real need (19:33, 20:01).
That is true and it is also the standard incumbent position, valuable mainly because trust is the one asset that cannot be built quickly. It is a genuine moat and it is not a strategy.
The more useful admission is about physical presence: branch networks will decrease significantly over the next decade, though banks themselves will not disappear because they serve important purposes (24:33, 25:00). That is a specific, falsifiable prediction from inside the industry, and it concedes distribution while defending function.
The regulatory point deserves the last word: outside pressure, including regulation, forces the institution to get better and is therefore part of why it can keep innovating (29:03).
Said from a stage where the adjacent argument is that a less regulated system will serve autonomous agents better, that is the real disagreement in the room. One side treats regulation as the cost of trust. The other treats it as the friction agents will route around. Neither says which one an agent's owner would choose when something goes wrong.
演讲章节
关键要点
- 01
The argument is that agents will transact in crypto because they will not carry cards, and blockchain is the more native interface for them. 15:03
- 02
Exchanges and stablecoins are named as the two proven businesses, with tokenisation and roughly a dozen government conversations as the next wave. 14:08
- 03
The panel's most direct voice calls these high-risk areas where value is speculative and building use cases is hard. 24:04
- 04
A specific falsifiable prediction: branch networks decrease significantly over a decade while banks themselves do not disappear. 24:33
- 05
Regulatory pressure is framed as part of why the institution can keep innovating, which is the real disagreement in the room. 29:03
提及的实体
相关演讲
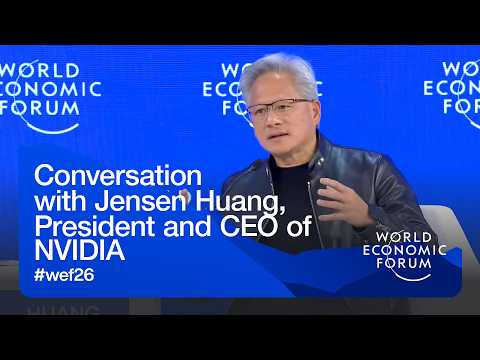
Huang brings a diagram to Davos: AI as a five-layer cake running energy, chips, cloud, models, applications — with economic benefit landing at the top and every layer below it a precondition. His argument for why this is a genuine platform shift rather than a product cycle is the strongest part, and it does not rest on his commercial position: software was pre-recorded and worked on structured data, whereas a machine that reasons about unstructured input and inferred intent makes previously impossible applications possible. What the framing accomplishes is worth noticing separately. By presenting the layers as a chain rather than a portfolio, it converts infrastructure spending from a bet into a prerequisite, and the question of proportion between layer-two spending and layer-five value stops being askable. Read against the GTC keynote two months later, the same business gets two framings: one a case for choosing his product, the other a case for the category existing at the scale he needs.

Harari spends most of his address establishing terms before asking the question he came to ask. His preliminary work is to dismantle the word tool: a knife's use is decided by whoever holds it, whereas what is arriving decides for itself, and can also invent new kinds of knives. From there he argues that anything constituted by words — law, books, text-centred religion — is exposed, while drawing a firm line at feeling, where he says there is no evidence at all. The structural claim is that the ancient tension between letter and spirit has always run inside humanity and is about to be externalised between humans and the new masters of words. Only then does he arrive at personhood, and his handling is precise: corporations, New Zealand rivers and Indian deities hold legal personhood safely because the decisions are made by humans behind the container. An entity that decides for itself ends that arrangement. He does not answer the question; he tells the room it is coming.

A show of hands opens the session: nearly everyone has piloted, far fewer have scaled, and everyone who scaled hit problems they did not anticipate. What makes the panel useful is where the four answers do not point. None of the executives — running a healthcare manufacturer, a payments network, an energy producer and a consultancy — blames model capability, cost or data infrastructure. All four describe an organisational constraint. McInerney's account is the sharpest and is an account of failure: eighteen months of executive advocacy and democratised model access produced nothing, until three hundred senior leaders were put in a room for two days and made to build agents themselves. Jakobs supplies the mechanism worth copying, measuring returned clinician time against the three to seven minutes a patient currently receives rather than against cost. Nasser rejects the premise that acquiring compute produces value, and locates returns in operations rather than in the back-office functions most organisations automate first.

A year after their first joint appearance, the heads of Anthropic and Google DeepMind returned to a shared stage and disagreed mainly about speed. Amodei held to a horizon of one to two years for systems that outperform humans across most cognitive work, resting the claim on a self-improvement loop that runs through code; Hassabis kept to the end of the decade, arguing that verifiable domains like coding and mathematics automate far earlier than natural science, and that the capacity to pose a new question rather than answer an existing one is still missing. The exchange is most useful where they converge: both accept the loop is the variable that decides everything, both are sceptical of doomerism without dismissing the risk, and both want more time than the competitive dynamic allows. Amodei's chip-export argument and Hassabis's call for minimum international safety standards are the two concrete policy asks.

The distinction in this session that deserves to travel is a two-word change: the model is moving from an attention economy to an attachment economy. That changes what is measured and what regulation would have to address, because attention competes for time while attachment competes for relationship, and the two produce different products from identical technology. Attention is finite in a way people notice; attachment produces reliance that feels like preference, which makes it harder to regulate for the same reason it is harder to notice. The supporting argument is about incentives rather than intent: earlier engagement produces more data and longer relationships. The regulatory proposal — measuring well-being outcomes rather than asking for safety by design — identifies the right target without solving the measurement problem that made regulators settle for a floor in the first place.

The most useful sentence is a diagnosis of how clients are getting it wrong: they see a cost opportunity rather than a revenue one. That framing decides everything downstream, because an organisation treating AI as cost reduction measures success by what disappears and arrives at a smaller version of what it already was. The market number offered — seventeen per cent index growth in 2025 that nobody foresaw — is deployed against bubble anxiety and argues in both directions, since unforecast gains are poor evidence for confidence in any current consensus. The panel then locates the real source of instability outside technology entirely, in three geopolitical situations generating enough uncertainty to dominate planning, which is a corrective worth taking seriously at a technology conference. Their closing question about thriving across multiple futures is correct and sits uneasily beside the cost framing they diagnosed at the start.